Summary
China, the world's largest log importer, is aggressively expanding domestic timber production capacity, a long-term trend that has drawn the attention of New Zealand's log export sector. Scott Downs, head of sales and key accounts at Stand Forestry, said China's new five-year forestry plan will reshape the log import market over the long term. Downs said Chinese domestic logs cannot yet compete with New Zealand radiata pine in high-end timber grades, and newly planted forests will take years to mature before harvesting.
The additional domestic supply will first hit the low-grade industrial log market, while New Zealand's high-quality radiata pine retains a competitive edge in the near term. Under the National Forestry and Grassland Administration's plan, China aims to raise forest stock volume to 22.4 billion cubic metres and forest coverage to 25.8 percent by 2030, with national reserve forest projects in the south continuing to expand. Chinese timber processors remain the largest buyers of New Zealand logs.
In the first half of this year, New Zealand's log imports to China edged down 3.1 percent, while China's softwood lumber imports fell by a sharper 20.2 percent over the same period. Downs said daily log consumption at Chinese ports held steady at 55,000 cubic metres in the first half, with softwood log inventories stable. Statistics New Zealand data showed the country's total exports to China rose NZ$191 million in August, with logs and wood products contributing NZ$40 million as the main driver.
The yuan's appreciation against the US dollar that month boosted the purchasing power of Chinese timber buyers. However, China's construction sector remains under pressure. New residential floor space started fell 24 percent year-on-year to 267 million square metres in the January-July period, with residential starts at 194.9 million square metres, weighing on timber consumption.
China's timber imports are diversified, averaging 115.9 million cubic metres annually over the past six years, with Russia accounting for nearly 30 percent. Facing China's expanding domestic timber capacity, New Zealand exporters are pursuing market diversification, targeting emerging markets in India and Southeast Asia while defending the high-end radiata pine segment. But the Indian market is unlikely to offer quick relief, with large volumes of unsold pine logs still piled up in the Kandla port bonded zone.
Industry players expect local timber demand to recover meaningfully only after the monsoon season ends and Diwali passes.
Commentary
China is New Zealand's largest log export market, and its push for timber self-sufficiency is gradually reshaping global log trade flows. New Zealand radiata pine remains irreplaceable in high-end structural timber thanks to stable supply and superior quality, but the low-grade industrial log segment will be the first to feel the squeeze from China's domestic fast-growing plantations and reserve forest projects. For small and medium-sized New Zealand forestry firms, minor short-term fluctuations in export volumes are not the main concern.
What matters is that China's import structure is shifting from volume expansion to quality screening. China's construction starts continue to slide and timber demand is soft, but the yuan's appreciation has lowered purchasing costs and provided a temporary buffer for New Zealand exporters. At the same time, Russian timber holds nearly 30 percent of the Chinese market and competes aggressively on price.
If New Zealand relies solely on traditional log exports, margins will come under further pressure. Notably, China's national reserve forest projects in the south mostly use fast-growing species such as eucalyptus and Chinese fir. Their harvest cycles are long, but policy support is strong, and they could eventually replace imports at scale in the low-to-mid-end market.
New Zealand companies should accelerate the shift from raw log exports to higher-value sawn timber and engineered wood products, and use tariff preferences under the upgraded China-New Zealand free trade agreement to tap customised demand in China's furniture manufacturing and fit-out markets. India and Southeast Asia are seen as promising, but infrastructure gaps and demand cycles will limit their ability to absorb China's share shift in the near term. The long-term competitiveness of New Zealand radiata pine lies in its sustainable certification and low-carbon attributes, which align with China's demand for green building materials under its dual-carbon goals.
Smaller firms can jointly promote environmental certification to lock in high-end customers.
Keywords: New Zealand logs, China timber self-sufficiency, radiata pine, Scott Downs, forest stock volume, log imports, market diversification, India market
Summary in Chinese | 摘要
中国作为全球最大原木进口国正大力提升国内木材生产能力,这一长期趋势引起新西兰原木出口行业重视。斯坦德林业销售与大客户负责人斯科特·唐斯分析,中国新一轮五年林业规划将在长远层面改变原木进口市场格局。唐斯认为,中国本土原木在高端材领域暂时无法与新西兰辐射松抗衡,新造林也需漫长培育周期才能采伐,新增国产木材将首先冲击低等级工业原木市场,新西兰高品质辐射松短期内仍保有竞争优势。
按照国家林业和草原局规划,到2030年中国森林蓄积量目标为224亿立方米,森林覆盖率提升至25.8%,南方国家储备林项目也在持续建设。现阶段中国木材加工厂依旧是新西兰原木最大采购方,今年上半年新西兰对华原木进口量小幅下降3.1%,同期中国软木锯材进口下滑幅度更大,达到20.2%。唐斯称,上半年国内港口原木日消耗量稳定在5.5万立方米,软木原木库存保持平稳。
新西兰统计局数据显示,8月该国对华出口整体增长1.91亿新西兰元,原木及木制品贡献4000万新西兰元,成为拉动出口的主力;当月人民币兑美元升值,提升了中国木材采购商的购买力。但国内建筑行业依旧承压,1至7月房企新开工建筑面积2.67亿平方米,同比下降24%,住宅新开工面积1.949亿平方米,建筑需求疲软制约木材消费。中国木材进口来源多元,过去六年年均进口木材1.159亿立方米,其中俄罗斯占比接近三成。
面对中国本土木材产能扩张,新西兰出口企业制定市场多元化策略,计划开发印度、东南亚等新兴市场,同时守住高端辐射松市场。不过印度市场短期并不乐观,坎德拉港保税区仍堆积大量未售出的松木原木,业内预计当地木材需求要等到雨季结束、排灯节之后才有望明显回暖。
Commentary in Chinese | 评论
中国作为新西兰原木最大出口市场,其国内木材自给战略的推进正逐步改变全球原木贸易流向。新西兰辐射松凭借稳定的供应和优良的材质,在高端结构材领域仍具不可替代性,但低等级工业原木市场将首先受到中国本土速生林和储备林项目的挤压。对于新西兰中小林业企业而言,短期出口量的小幅波动并非关键,真正需要关注的是中国进口结构从“量的扩张”转向“质的筛选”。
当前中国建筑行业新开工面积持续下滑,木材需求疲软,但人民币升值带来的采购成本下降为新西兰出口商提供了阶段性缓冲。与此同时,俄罗斯木材在中国市场的份额接近三成,且价格竞争激烈,新西兰若仅依赖传统原木出口,利润空间将被进一步压缩。值得留意的是,中国南方国家储备林项目多采用桉树、杉木等速生树种,其出材周期虽长,但政策扶持力度大,未来可能在中低端市场形成规模替代。
新西兰企业应加速从原木出口向高附加值锯材、工程木产品转型,并利用中新自贸协定升级后的关税优惠,拓展中国家具制造和装修市场的定制化需求。印度和东南亚市场虽被寄予厚望,但短期受制于基础设施和需求周期,难以迅速承接中国市场的份额转移。新西兰辐射松的长期竞争力在于其可持续认证和低碳属性,这与中国“双碳”目标下的绿色建材需求相契合,中小企业可联合推广环保认证,锁定高端客户。
关键词: 新西兰原木, 中国木材自给, 辐射松, 斯科特·唐斯, 森林蓄积量, 原木进口, 市场多元化, 印度市场
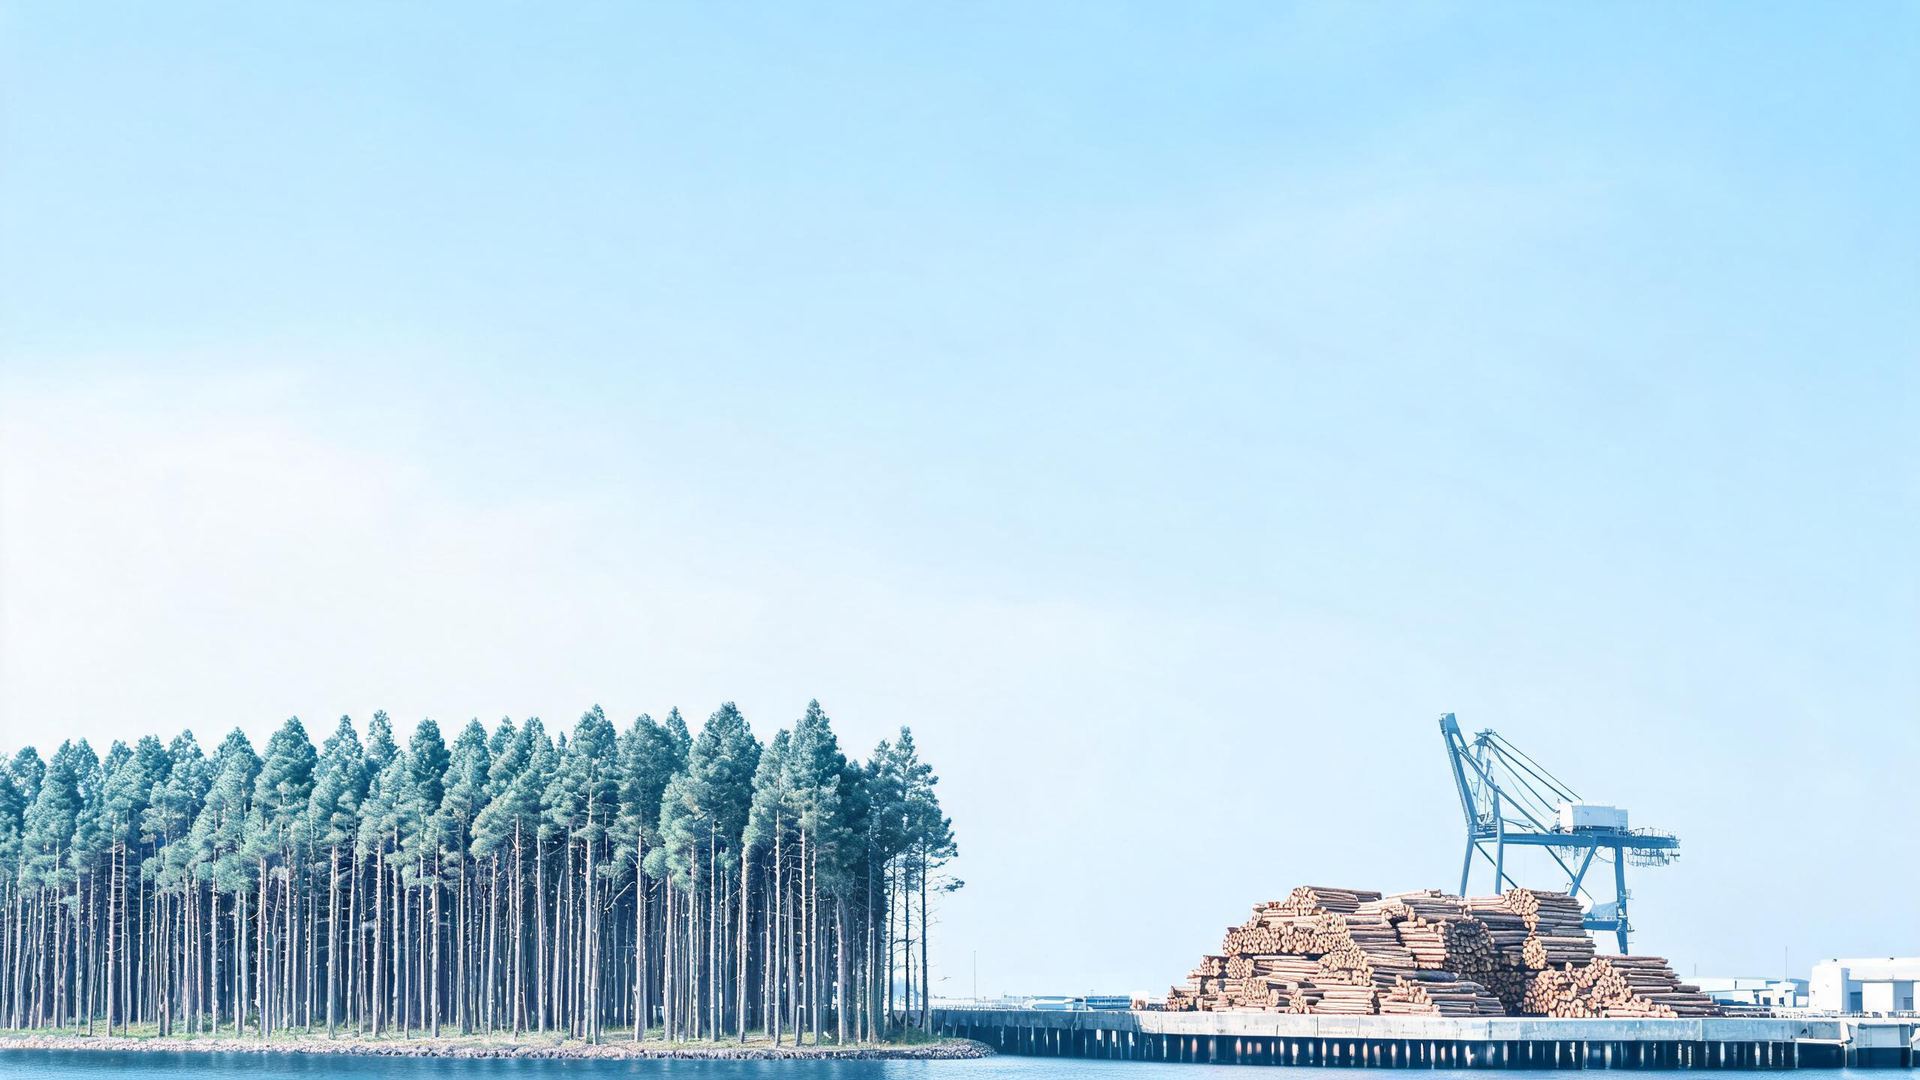
Source: China Timber and Wood Products Distribution Association
Disclaimer: This article is compiled from publicly available sources for general information only. The analysis and commentary are editorial opinions. MiDeer Observer does not guarantee the accuracy or completeness of the information provided. Readers should seek independent professional advice before relying on this content, or contact us for more information.
免责声明:本文基于公开信息编译,仅供一般性参考。文中分析与评论为编辑观点。MiDeer Observer 不对所提供信息的准确性或完整性作出保证。读者在依赖本文内容前,应寻求独立专业意见,或联系我们获取更多信息。