Summary
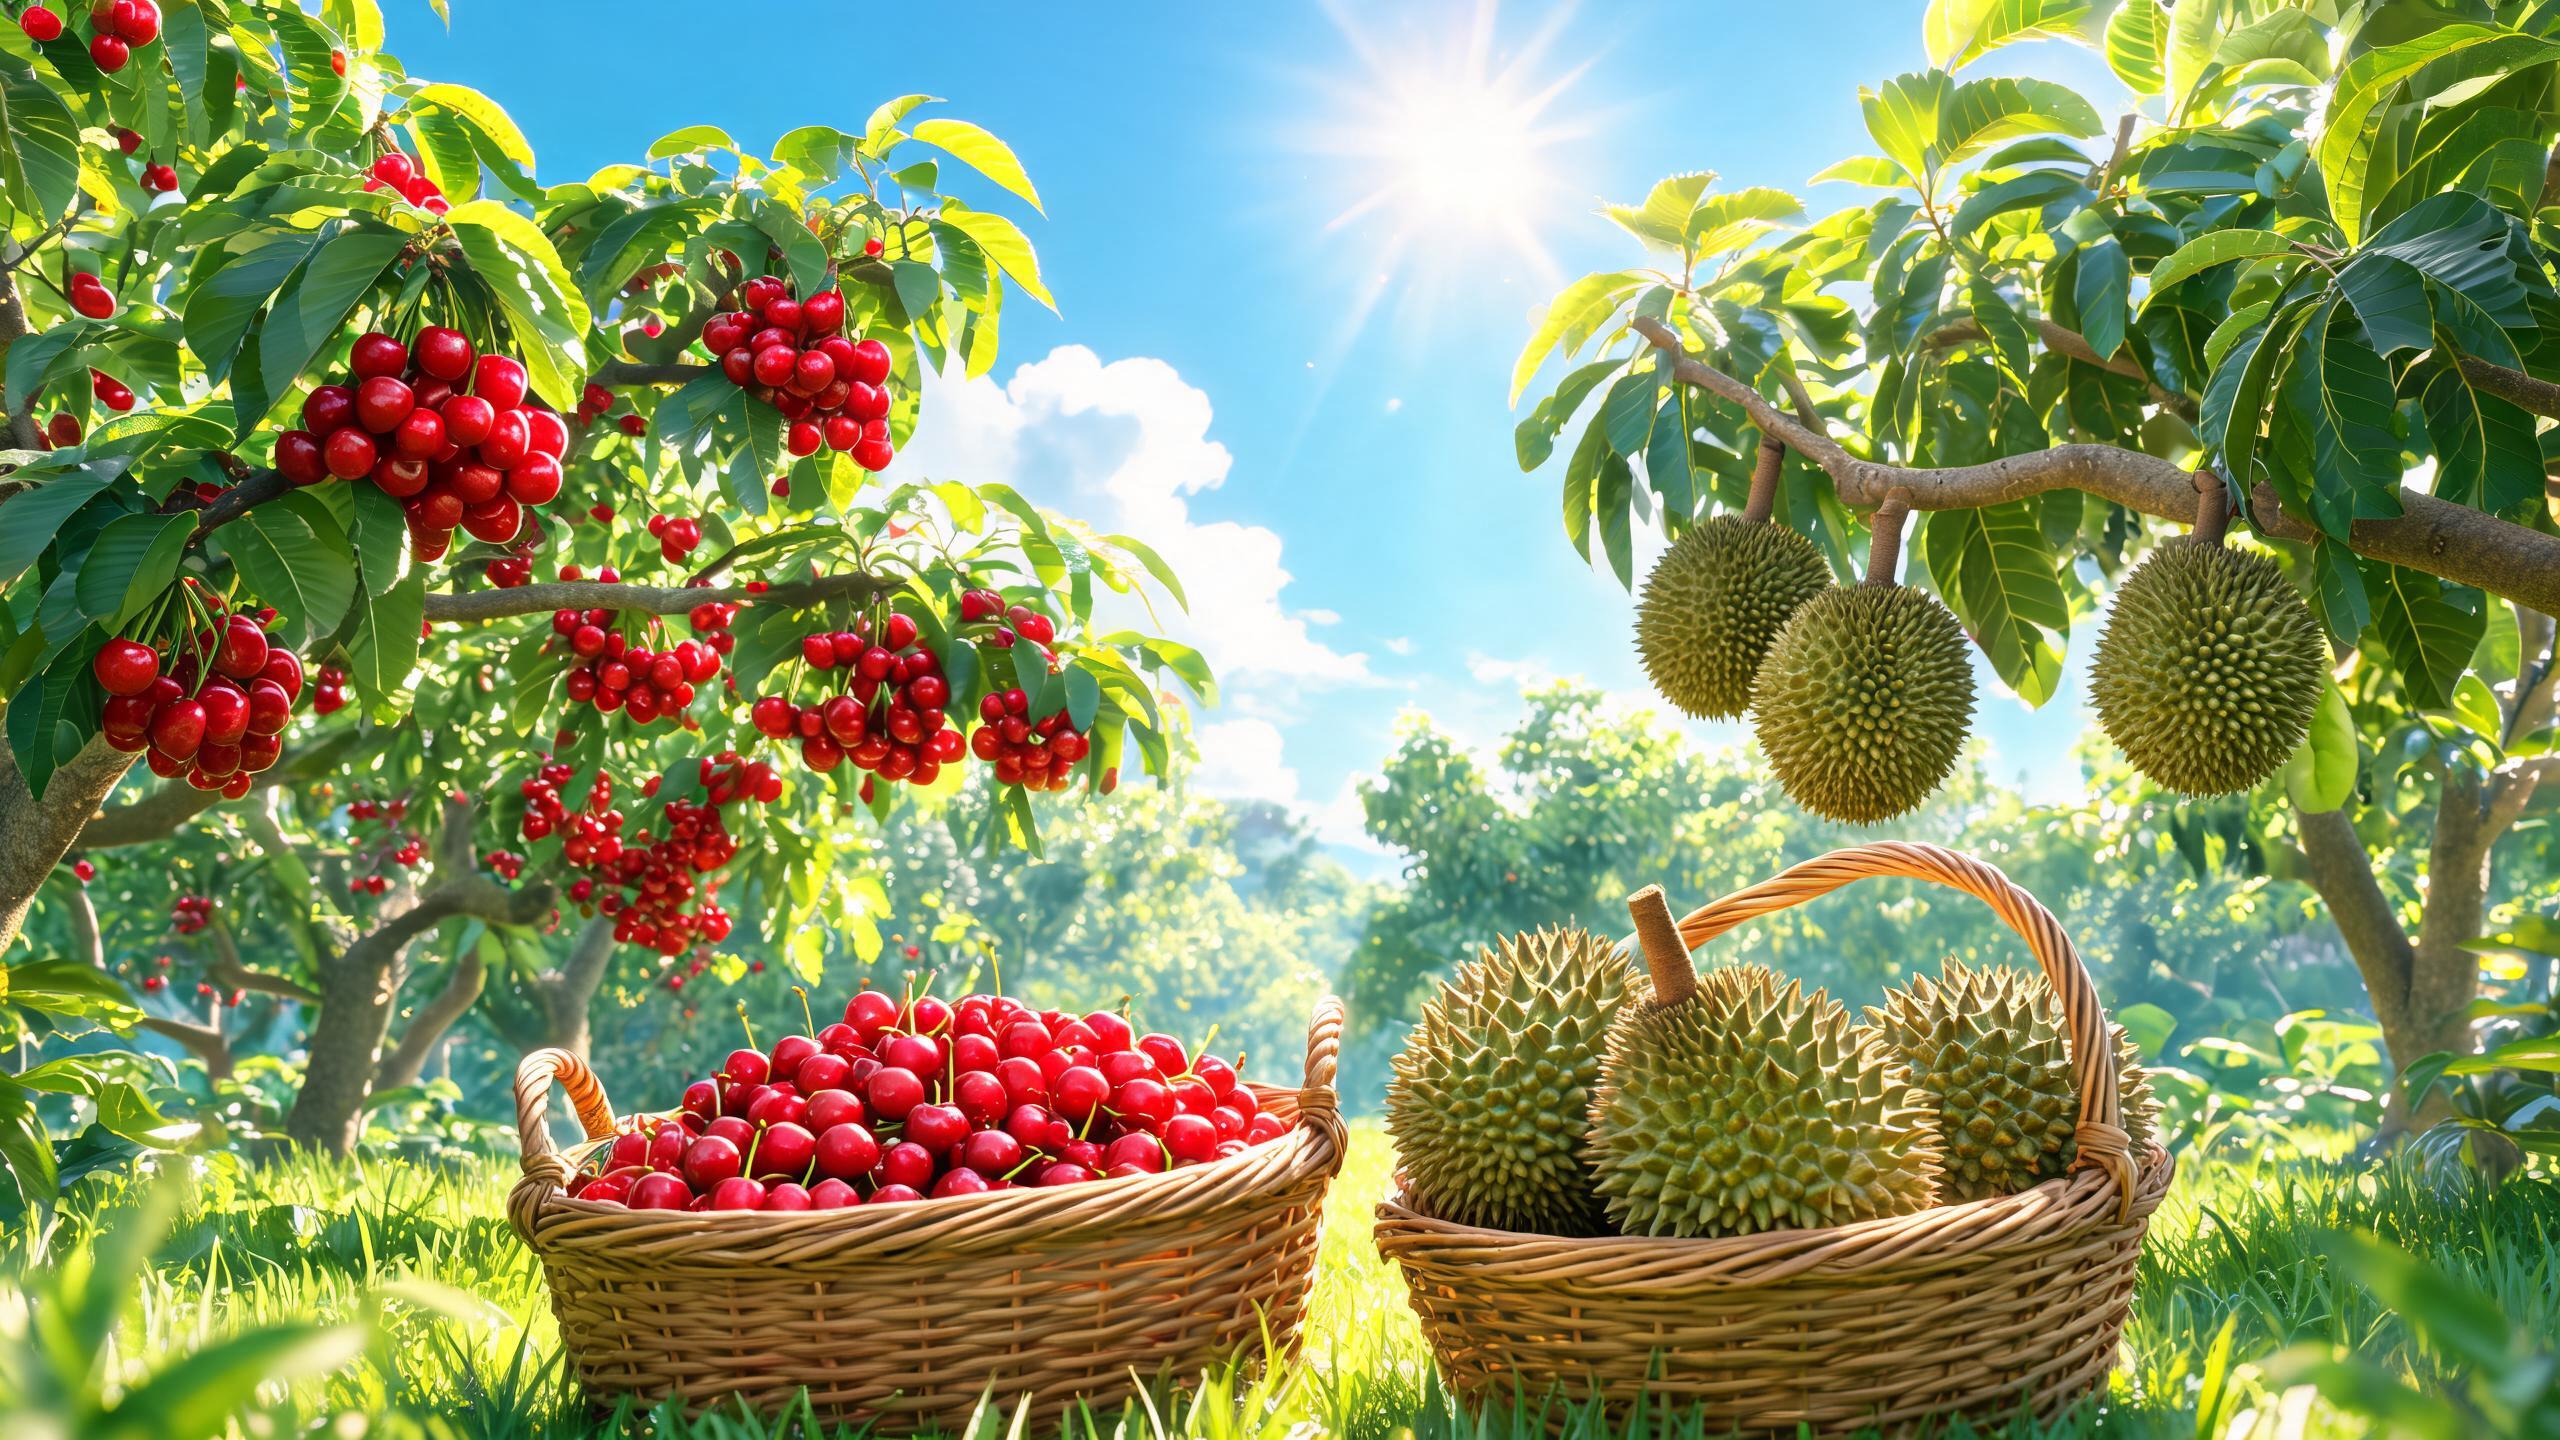
Imported durian and cherry prices have dropped to their lowest levels in nearly three years. Thai durian output is forecast at 2.07 million tonnes in 2026, while Vietnam's planted area has expanded nearly fivefold over the past decade, with the two countries accounting for over 97 percent of China's durian imports. Chilean cherry production stands at 655,000 tonnes, with over 90 percent shipped to China.
Combined with the zero-tariff provisions of RCEP and a 60 percent reduction in logistics costs on the China-Laos railway, durian prices have fallen 40 percent year on year, and wholesale cherry prices have occasionally dipped to 25 yuan per jin.
Commentary
The halving of imported fruit prices in China reflects a reshaping of the regional supply landscape, driven by RCEP benefits and improved logistics efficiency on the China-Laos railway. Surging supplies of Thai and Vietnamese durians and Chilean cherries benefit consumers in the short term, but put price pressure on New Zealand's premium fruit exporters. For NZ SMEs in import distribution,
the low-price window offers a chance to optimise inventory; for exporters of kiwifruit and apples, strengthening quality or niche positioning is essential to avoid a price war.
Keywords: imported fruit, durian, cherries, falling prices, output growth, supply-demand imbalance, RCEP, China-Laos railway
Source: Sina
Disclaimer: This article is compiled from publicly available sources for general information only. The analysis and commentary are editorial opinions. MiDeer Observer does not guarantee the accuracy or completeness of the information provided. Readers should seek independent professional advice before relying on this content, or contact us for more information.